A monetary policy is not a list of new rules for borrowers. It is a set of settings for the central bank's own instruments and a set of targets. For a business, the work is to read how those settings feed through to the rate and the availability of credit from its own bank.
The settings for FY 2081/82
The NRB works with an interest rate corridor. Its policy rate sits in the middle, the deposit collection rate forms the lower boundary and the bank rate forms the upper boundary. Banks lend surplus liquidity to the NRB at the lower rate and borrow from it at the upper one, so the corridor limits how far the interbank rate can move.
At the first quarterly review of FY 2081/82:
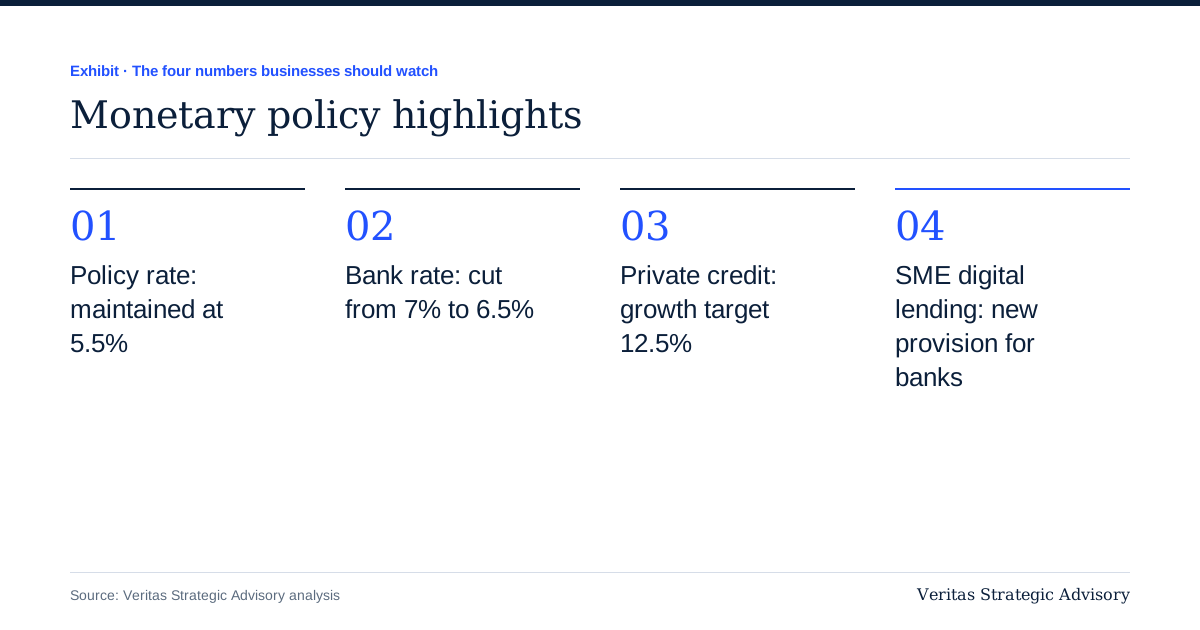
the policy rate was reduced from 5.5% to 5.0%
the bank rate, the upper limit of the corridor, was reduced from 7.0% to 6.5%
the deposit collection rate was 3.0%
the cash reserve and statutory liquidity ratios were maintained at existing levels
The weighted average interbank rate was around 3.0% in the first quarter, near the bottom of the corridor, which is a sign of ample liquidity.
The targets, and what happened
For the year, the policy set targets for inflation of around 5%, broad money growth of 12%, private sector credit growth of 12.5% and foreign exchange reserves covering at least seven months of imports.
By Ashwin 2081, the picture was uneven: inflation was within target (about 4.8% point-to-point), reserves covered about 14.6 months of imports, broad money growth was above its target, but private sector credit growth was only about 6%, roughly half of the target.
Why cheaper money did not mean easier loans
Three factors commonly cited for the gap:
Demand, not supply, may be the constraint. With ample liquidity in the system, as the low interbank rate suggests, a lower policy rate cannot by itself create demand for credit.
Risk appetite. Banks lend only to borrowers whose numbers and security they trust, and a lower rate does not change that assessment.
Transmission is gradual. Banks reprice lending through their base rate and spread. Changes in the policy rate reach existing and new borrowers at different speeds and rarely in full.
The practical result for borrowers: the cost of funds fell, but a bank's decision to lend still turned on the quality of the borrower's numbers and security.
How to read a monetary policy as a borrower
Use this checklist each year:
The corridor. Did the policy rate and bank rate move, and by how much? This is the signal for the direction of the base rate.
Ratios that limit lending. The credit-to-core capital and deposit ratio and the reserve ratios decide how much room your bank has.
Sectoral requirements. Priority-sector and productive-sector lending requirements affect which borrowers a bank wants.
Import and foreign exchange provisions. Letter of credit margin rules and rules on holding foreign currency affect working capital for importers and exporters.
Targets versus actuals. A target that was missed tells you where the next adjustment is likely to come.
Many of the operational rules sit in NRB's directives, not in the policy speech. Check the current unified directives for the figures that matter to your facility.
What to do with it
Ask your bank when it will reprice your facility's base rate after a corridor change, and what the contract says about the spread.
Update your cash flow forecast with the new rate, and test it with a rate that is a point higher.
Use the quarter when liquidity is plentiful to refinance or extend a facility, if your numbers and security are in order.
Prepare the lender's file before you ask: management accounts, projections and a clear use of funds. A bank deciding whether to lend looks at that, not at the policy rate. Our guide on why a bank rejects a loan covers the usual reasons.
If you want help testing a financing plan against the current rate environment, our team of chartered accountants can work through it with you.
---
*Prepared from published reports of NRB's monetary policy for FY 2081/82 and its first quarterly review, October 2026. General guidance, not advice on your circumstances. For the current year, read NRB's latest policy and directives.*