
- service fee to a VAT-registered resident
- 1.5%
- service fee to an unregistered recipient
- 15%
- rent with a source in Nepal
- 10%
- from month end to deposit
- 25 days
Withholding tax is the most routine thing a finance team does and one of the most commonly got wrong. The rate itself is rarely the problem. The problem is applying the right rate to the wrong base, missing a deduction entirely, or discovering three years later that a position taken on a supplier payment cannot be supported.
This is the FY 2083/84 position on the payments most businesses make, followed by the errors we see most often. Rates follow the Inland Revenue Department schedule under sections 87, 88, 88Ka, 89 and 95Ka of the Income Tax Act 2058.
What are the TDS rates in Nepal for FY 2083/84?
Service fee, commission, consultancy, 1.5% or 15%
Where the recipient is registered for VAT, deduct 1.5% under section 88(1)(4). Where they are not, the general rate under section 88(1) is 15%. The same also applies at 1.5% to a resident entity dealing in VAT-exempt transactions.
This single distinction accounts for more corrections than any other. Check the PAN or VAT certificate before you decide, not after.
Contract or agreement, 1.5%
Section 89(1) applies to contract payments exceeding Rs. 50,000. A single payment of Rs. 50,000 or less falls outside it, but payments to the same party under the same contract are aggregated. Splitting an invoice does not avoid the deduction.
Payments under a contract to a non-resident carry 5% under section 89(3)(ka), and that deduction is final.
Rent, 10%, or nothing
Rent with a source in Nepal paid by a resident person carries 10% under section 88(1)(5). House rent received by a natural person is outside the Act's withholding provisions, municipal rent tax applies instead.
Vehicle hire from a VAT-registered vehicle-rental business drops to 1.5% under section 88(1)(5)(ka).
Freight and transport, 1.5% or 2.5%
Carriage services and transport hire carry 2.5% under Section 88, reduced to 1.5% where the recipient is a VAT-registered transport business. Confirm the clause and rate in the current Act.
Dividend, 5%, final
Section 88(2)(ka). Final withholding under section 92: the recipient adds nothing to their return and pays nothing further.
Interest, 15%, 6%, or nothing
The general rate is 15%. Interest on deposits, debentures or government bonds paid to a natural person, not connected with a business, by a bank, financial institution, cooperative, debenture issuer or listed company carries 6% under section 88(3), and is final. Interest paid to a resident bank or financial institution is not subject to withholding at all.
Insurance agent commission, 20%
A high rate, frequently applied at 15% in error. The rate was raised by the 2083/84 Finance Bill, so confirm the rate and the clause in the enacted Finance Act before you rely on it.
How do you calculate TDS on a bill amount in Nepal?
To calculate TDS on any commercial invoice or bill in Nepal, always apply the withholding rate strictly to the VAT-exclusive taxable base, never to the VAT amount:
Isolate the Taxable Base: On an invoice of Rs. 100,000 + 13% VAT (Rs. 13,000) = Total Rs. 113,000, the withholding base is strictly Rs. 100,000.
Verify Provider PAN/VAT Status: Deduct 1.5% (Rs. 1,500) if the vendor is VAT-registered. Deduct 15% (Rs. 15,000) under Section 88 if unregistered.
Compute Net Payment: Net cheque/bank transfer to vendor = Total Invoice minus TDS withholding.
*Tip: For automated calculation across rent, consultancy, transport, and salary slabs, use our free Nepal TDS Calculator.*
What TDS applies to vehicle hire and passenger transport?
Withholding on transport and vehicles in Nepal depends strictly on whether the vehicle is rented or cargo/passengers are carried:
Public Passenger & Freight Transport: 2.5% under Section 88(1)(8), reduced to 1.5% when provided by a VAT-registered transport enterprise.
Vehicle Hire / Rental: Car and vehicle rental from a VAT-registered rental company carries 1.5% under Section 88(1)(5)(ka).
Municipal Transport Taxes: Local governments collect municipal passenger levies separately; these do not substitute for federal income tax withholding under the Income Tax Act.
Where do businesses actually lose money on TDS?
1. Deducting on the VAT-inclusive amount. Withholding applies to the taxable value of the payment, not to the VAT charged on it. On a bill of Rs. 100,000 plus Rs. 13,000 VAT, deduct on Rs. 100,000. Deducting on Rs. 113,000 costs the supplier money and does not discharge any additional obligation.
2. Treating an unregistered service provider as registered. The gap between 1.5% and 15% is ten times the tax. On a year of consultancy payments this becomes a material short-deduction exposure, and the liability sits with the payer.
3. Splitting contracts under Rs. 50,000. Aggregation under the same contract is explicit. This is one of the first things an assessment tests.
4. Missing the deduction on a foreign payment. Payments to non-residents carry withholding, and the treatment can be affected by a tax treaty. The treaty position must be documented at the time, not asserted later.
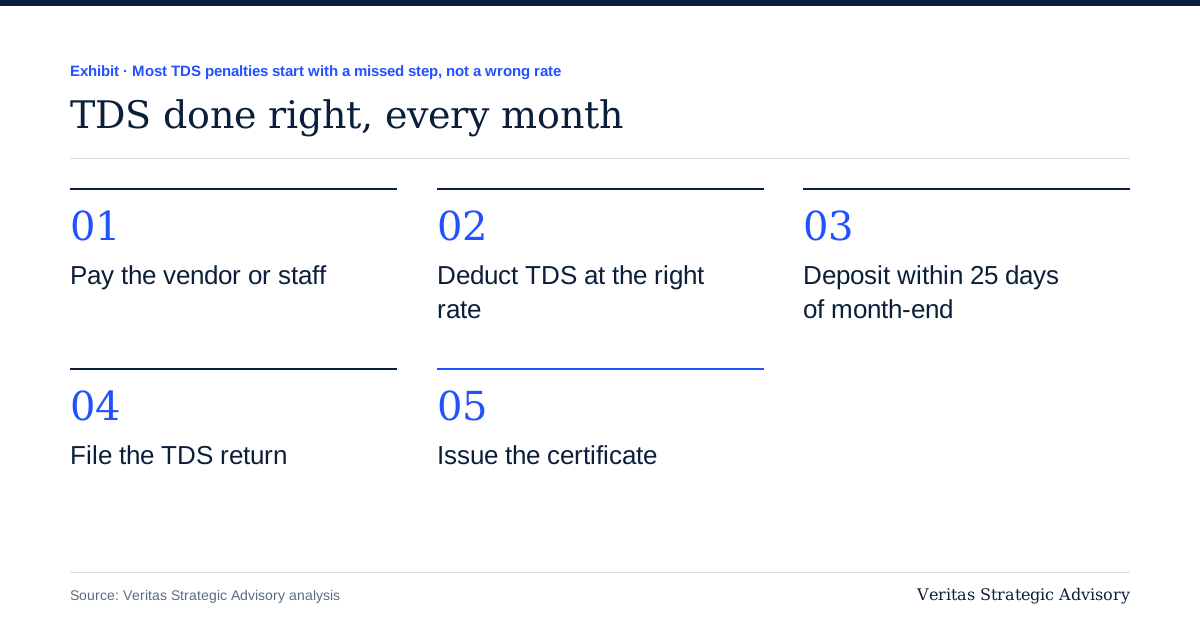
5. Late deposit. The tax withheld must be deposited by the 25th of the following Nepali month, with the e-TDS return for that period. Late deposit attracts interest and a fee, and the delay is visible on the record permanently.
6. No file behind the position. Where a rate depends on a fact, VAT registration, residence status, the nature of a contract, the evidence for that fact should be on file when the payment is made. Assessments are answered from documentation, not from recollection.
What control stops TDS errors before they happen?
Most withholding errors are not judgement failures. They are process failures: nobody checks the supplier's registration status before the first payment, and nothing in the system flags a payment type that carries an unusual rate.
Two controls remove most of the risk:
A supplier master that records PAN, VAT registration status and residence, updated at onboarding rather than at payment.
A payment-type field on every voucher that maps to a rate, so the rate is a lookup rather than a decision made under time pressure.
Neither is expensive. Both are cheaper than an assessment covering three years of payments.
Frequently asked questions
When must TDS be deposited in Nepal?
Within 25 days of the end of the month in which the payment was made. A statement of the withholding is filed with the relevant Inland Revenue Department office; the statement and the payment may be submitted together or separately.
Which revenue code is withheld tax deposited under?
There is no single TDS heading. Tax is deposited under the revenue heading for the type of income it was withheld on: remuneration under 11112, rent and lease income under 11131, interest under 11132 and dividends under 11133. The full Inland Revenue Department list is in our tax FAQ on paying tax and revenue codes. Depositing under the wrong heading is correctable, but it has to be chased through the tax office, the bank and the District Treasury Controller Office.
What is the TDS rate on a service fee in Nepal?
1.5% where the recipient is a resident registered for VAT, under section 88(1)(4), and 15% under the general rate in section 88(1) where they are not. The 1.5% rate also applies to a resident entity dealing in VAT-exempt transactions. Check the PAN or VAT certificate before the first payment, not after.
Is there a minimum amount below which TDS does not apply?
For contract payments under section 89(1) the threshold is payments exceeding Rs. 50,000. Payments to the same party under the same contract are aggregated, so splitting an invoice does not take it below the line.
Does TDS apply to payments made to a party outside Nepal?
Yes, and the rate and finality differ. A contract payment to a non-resident carries 5% under section 89(3)(ka) and that deduction is final. The wider position, including treaty relief, is set out in TDS on payments to foreign vendors in Nepal.
What happens if the wrong rate was applied for three years?
The shortfall remains the withholding agent's liability, with interest and fees, and it is usually discovered in an assessment rather than by the business. See how the IRD selects companies for tax audit.
---
*Rates stated are those applicable for FY 2083/84 and are subject to amendment by the Finance Act. Several treatments depend on facts specific to the payment, residence status, treaty relief, exemption certificates, the terms of the contract. This is a general guide, not advice on a particular payment.*
*Our TDS rate calculator covers 32 payment types with the section reference for each. Where an amount is material, have the position checked before the payment is made.*


