Published 17 September 2026. Source: Ministry of Finance, "पुँजी बजार सुदृढीकरण तथा पुनरूत्थान कार्ययोजना, २०८३", full text as publicly released.
The document outlines a shift toward varied trading tools, institutional support, and flexible corporate financing.
Here is an analysis of what these policy intentions mean in practice for both retail participants and enterprise owners, alongside the operational hurdles that stand in the way.
1. Retail Investors: Taxation, Leverage, and Exposure Risks
Historically, Nepal's secondary market penalized active trading through a transaction-level capital gains tax that ignored intra-year losses. The action plan addresses this and expands how investors can navigate market cycles.
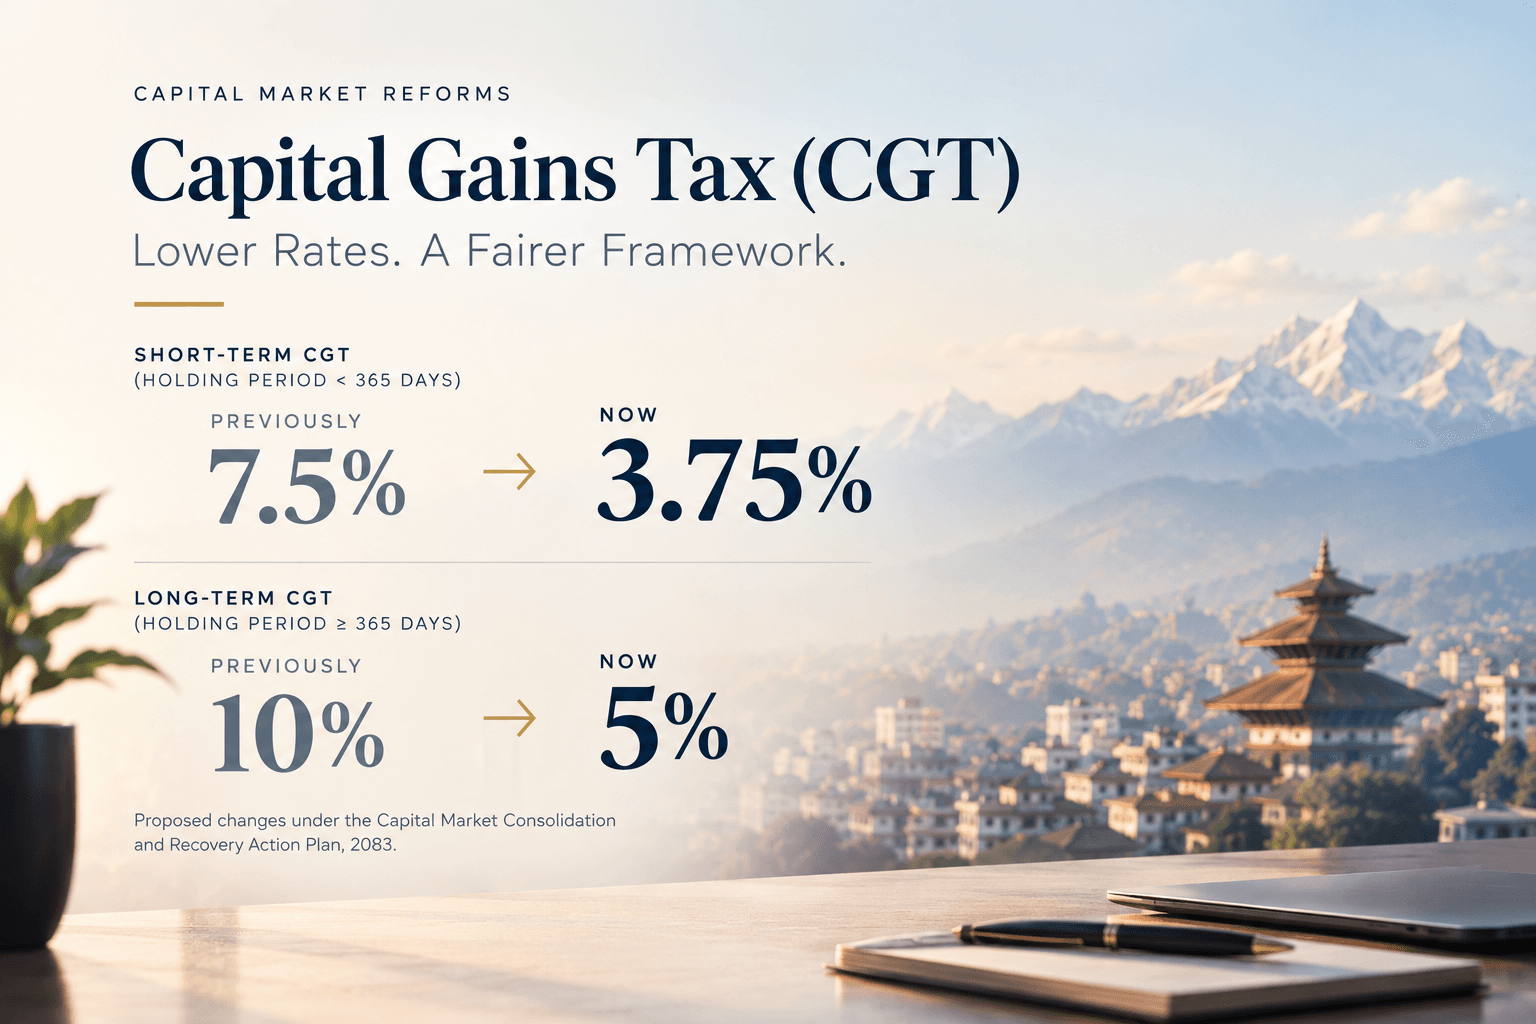
Tax netting and rate reductions. The plan introduces an automated loss-adjustment mechanism. Losses can now offset gains within the same income year before a final tax is withheld through the clearing system. The plan proposes to cut the tax on these net profits to 3.75% for holdings over 365 days and 5% for shorter durations, against the 7.5% and 10% final-tax rates now in force from the 2083/84 budget. The reduced rates are a proposal until they are enacted. While this removes a major tax distortion, total transaction friction will still depend heavily on broker commissions and DP charges.
Intraday, short selling, and SLB. The market has long been restricted to long-only exposure. Moving forward, the framework seeks to legalize intraday trading, short selling, and securities lending and borrowing (SLB). These tools allow investors to hedge portfolios or profit from declining prices. However, short selling in a retail-heavy market introduces severe structural risks, including margin calls, borrowing costs, and theoretically unlimited losses if a shorted stock rallies.
Decentralizing leverage. Retail investors currently rely on commercial banks for share loans, facing rigid lending caps and shifting central bank risk weights. Allowing licensed stockbrokers to provide margin loans directly by Poush 2083 bypasses this bottleneck. This shifts credit risk directly to broker balance sheets, meaning access will likely be restricted to clients of well-capitalized brokerages with strict automated liquidation protocols.
Share splits. Allowing companies to split their shares below the traditional Rs. 100 face value improves retail accessibility for high-priced blue-chip stocks. A split does not alter a company's valuation or make it fundamentally cheaper; it simply reduces the minimum cash required to execute a trade, potentially boosting secondary liquidity.
2. Business Owners and Corporate Issuers: Beyond Bank Debt
Nepal's capital market has historically offered enterprise owners few funding avenues outside of commercial bank loans. This action plan introduces tools for balance-sheet management and alternative capital raising.
Corporate debt expansion. The plan incentivizes corporate, green, and disaster-recovery bonds by Ashwin 2083, allowing capital-intensive businesses to lock in fixed-rate, long-term financing that matches their asset lifecycles. Proposed amendments to the Securities Act will permit non-listed private companies to issue debt instruments, opening capital-market funding to businesses not yet ready for an IPO.
Market-driven IPO pricing. Traditional pricing formulas often fail to capture the earnings capacity of non-financial firms. Directing SEBON to introduce a price discovery (book-building) mechanism for sectors like manufacturing, hospitality, and agriculture by Poush 2083 allows institutional demand to dictate issue prices.
Defensive share buybacks. Listed companies will be permitted to use retained earnings to buy back their own shares by Magh 2083. This provides management with a defense mechanism against irrational market undervaluation, effectively reducing outstanding shares and boosting earnings per share.
Private equity, venture capital, and NRNs. Mandating a regulatory framework for PE/VC by Poush 2083 creates a formal pipeline for early-stage enterprises to access risk capital and eventually execute public exits. Amending the Foreign Investment and Technology Transfer Act (FITTA) by Ashwin 2083 to allow Non-Resident Nepali (NRN) participation introduces a highly necessary offshore liquidity channel.
3. Impact Overview: Intent vs. Dependency
| Dimension | Policy Intent | Key Implementation Dependency |
|---|---|---|
| Taxation | Tax applied only on net annual gains at reduced rates (proposed 3.75% / 5%) | Requires seamless API integration across broker systems (TMS), CDSC, and the Inland Revenue Department |
| Trading Tools | Intraday, short selling and SLB deployed for broader trading strategies | Demands robust automated surveillance, a functioning SLB mechanism, and a well-capitalized Settlement Guarantee Fund |
| Leverage | Margin trading provided directly by stockbrokers | Relies on broker capital adequacy and real-time collateral valuation rules to prevent cascading defaults |
| Corporate Debt | Diversified funding via corporate bonds and private company debt issuance | Requires institutional demand, credible credit-rating agencies, and legally enforceable insolvency and recovery mechanisms |
4. Implementation Realities and Systemic Risk
This action plan is an agenda of intent, not an immediate operational reality. Its success rests entirely on overcoming deep infrastructural and regulatory bottlenecks within ambitious deadlines between Ashwin and Falgun 2083.
For tax netting, intraday execution, and short selling to function without triggering systemic settlement failures, the software architecture across the entire financial ecosystem requires a massive, coordinated overhaul. Introducing complex derivative-like instruments into a retail-dominated exchange risks amplifying market volatility if not paired with strict financial literacy mandates and automated surveillance. The most viable near-term victories lie in the corporate debt and PE/VC provisions, which require less retail integration and can immediately diversify how Nepali enterprises fund their growth.
5. The Cost of a Reactive Tax Policy
This plan is being read by the market as a response to two immediate pressures: recent flood damage to listed physical assets, and a prolonged lack of trading activity. That context matters, because tax provisions written to revive sentiment quickly carry a different risk profile than tax provisions written on a stable, long-term timetable.
Frequent tax policy change has real costs beyond the rate itself. Businesses lose the ability to plan multi-year capital decisions against a stable tax basis. Compliance costs rise every time systems, staff and client advisories have to be reworked for a new provision. Ambiguity over effective dates and transitional treatment becomes a direct source of IRD disputes. Investors, foreign and domestic, price policy instability into their required return, which raises the effective cost of capital for Nepali issuers even where the underlying reform is sound. And each reversal or revision makes the next incentive announcement less credible, which blunts its effect before it is even implemented.
None of this argues against the reforms in this plan on their merits. It argues for treating any rate changes that are enacted as durable commitments rather than a sentiment lever to be adjusted again at the next quiet quarter, since the credibility of a 3.75%/5% rate depends on businesses believing it will still be 3.75%/5% two years from now.
How Veritas Can Help
For business owners, the corporate bond and private debt provisions are the most immediately actionable: they open a funding route beyond bank debt, well before the retail-facing trading mechanics are operationally ready. Talk to our team about whether debt issuance or a PE/VC-ready structure fits your financing plans.