
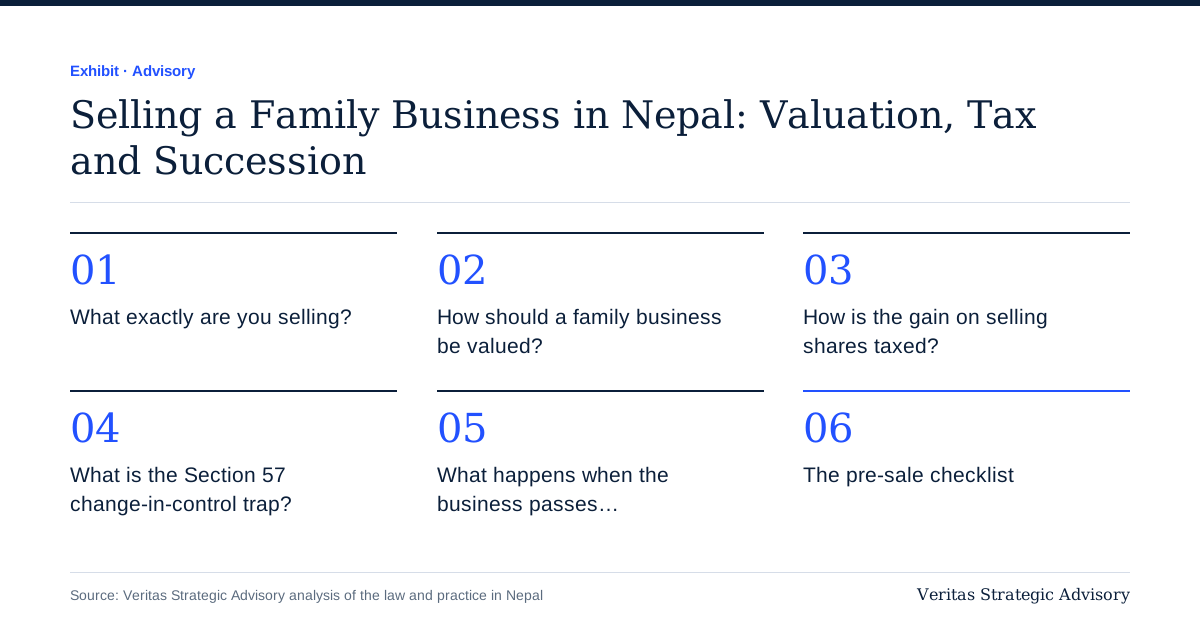
- Withholding on unlisted share gains, resident individual
- 10%
- Withholding on share gains, resident entity
- 15%
- Ownership change that triggers Section 57
- 50%
- Years Section 57 looks back
- 3
Most family businesses in Nepal are never sold in a planned way. They pass to a son or daughter when the founder steps back, they are split between brothers after a disagreement, or a buyer appears with an offer and the family scrambles to decide what the company is worth. Each of these is a sale or transfer of value, and each has a tax and valuation consequence that is far cheaper to plan for than to discover.
This guide is for owners of private limited companies and family-held firms in Nepal who are thinking about selling all or part of the business, bringing in an outside buyer, or handing it to the next generation. It covers the rules as they apply in fiscal year 2082/83 under the Income Tax Act, 2058 and the Companies Act, 2063. Rates and sections should be confirmed against the current Finance Act before any transaction is signed.
What exactly are you selling?
The first question is not price. It is what is changing hands. A family business can be sold in two broadly different ways, and the tax and paperwork differ sharply between them.
| Route | What the buyer gets | Who pays tax on the gain | Main paperwork |
|---|---|---|---|
| Share sale | The shares of the company, with all its history | The selling shareholder, on the gain on shares | Share transfer filed with the Office of the Company Registrar |
| Asset sale | Selected assets: land, building, machinery, stock, brand | The company, on the gain on each asset | Asset transfer deeds, VAT on taxable goods, land registration |
| Gradual transfer | Shares moved to family members over time | Depends on whether it is a sale, gift or inheritance | Share transfers plus family settlement records |
In practice most sales of an operating Nepali company are share sales. The buyer steps into the company as it stands, which means it also inherits the company's tax history, its unpaid liabilities and any open assessments with the Inland Revenue Department. That is why a buyer's financial due diligence focuses so heavily on the last four or five years of returns.
How should a family business be valued?
A valuation is not a single correct number. It is a range that two informed parties can defend. For a private company in Nepal there is no market price to point to, so the value has to be built from the business itself. Three methods are used, usually together:
Earnings-based. Normalised profit multiplied by a multiple that reflects risk and growth. "Normalised" matters: family businesses often pay relatives above or below market salaries, run personal expenses through the company, or rent property from the owner at an informal rate. Each of these has to be adjusted before the profit means anything to a buyer.
Cash flow (DCF). Future free cash flows discounted to today. This is the method Nepali courts have looked at in Section 57 disputes, so it carries weight when the IRD later questions the value used.
Net assets. The fair value of assets less liabilities. This sets a floor, and it dominates for asset-heavy businesses such as property holding companies, hotels or manufacturers with significant land.
Our longer piece on what determines a company's valuation explains how each method behaves. The point for a family seller is simpler: the value a buyer will pay depends on how much of the profit survives once the family steps back. If the customers, the bank relationship and the supplier credit all sit with the founder personally, a buyer will discount heavily for that risk.
How is the gain on selling shares taxed?
Under Section 95A of the Income Tax Act, 2058, the gain on disposal of shares in a resident company is subject to withholding at the time of transfer. As summarised by Pioneer Law and Niti Partners, the rates for unlisted shares are:
| Seller | Withholding on gain |
|---|---|
| Resident individual | 10% |
| Resident entity (company, firm) | 15% |
| Non-resident | 25% |
For an unlisted company, the company whose shares are being transferred is responsible for collecting the withholding before it records the transfer in its share register. That is a point many family companies miss: the company itself carries the obligation, not only the seller.
A worked example
The figures below are illustrative, not a client case.
Ram owns 60% of a family manufacturing company in Biratnagar. He subscribed for his shares at a total cost of Rs 60 lakh. An outside buyer agrees to pay Rs 4.2 crore for his 60% stake.
| Item | Amount (Rs) |
|---|---|
| Sale price of 60% stake | 4,20,00,000 |
| Less cost of shares | 60,00,000 |
| Gain | 3,60,00,000 |
| Withholding at 10% (resident individual) | 36,00,000 |
| Net cash to Ram before other costs | 3,84,00,000 |
If Ram had instead held the shares through a family holding company, the withholding would be 15% on the same gain, Rs 54 lakh. Structure matters, and it has to be decided years before the sale, not in the final week.
What is the Section 57 change-in-control trap?
This is the rule that catches most family sellers by surprise. Under Section 57, if the ownership of an entity changes by 50% or more compared with its ownership three years earlier, the entity is treated as having disposed of its assets and liabilities. Only shareholders holding 1% or more, and their associated persons, are counted when measuring the change.
In Ram's example, a buyer taking 60% crosses the 50% line. The company can then be treated as having sold its own assets at market value immediately before the change, and the period before and after the change is treated as separate income years. Tax losses and certain carried-forward positions can be lost. This is a charge on the company, separate from the withholding on Ram's personal gain.
Two recent developments matter. First, the Supreme Court in the Apollo Investment matter (2024) observed that a transfer from a father to his sons within the same household does not necessarily amount to the change in effective control Section 57 is aimed at, as reported by Mondaq. Second, a 2026 IRD clarification, reported by Niti Partners, states that non-voting preference shares are not counted in the 50% test. Neither removes the rule for an outside buyer, but both shape how a family transition can be planned.
What happens when the business passes by inheritance?
Not every succession is a sale. When ownership passes because the owner has died, Section 44 treats the heir as having acquired the property at its market value at that time, and that value becomes the heir's cost. If the heir later sells, the gain is measured from that market value, not from what the founder originally paid.
Transfers between spouses are dealt with separately under Section 43. Gifts during the owner's lifetime are a different matter again, and the treatment depends on how the transfer is documented. Because the outcome turns on the exact facts, a lifetime handover to children should be reviewed with a tax adviser before shares move, not after.
The non-tax side of succession is often harder. A founder handing over to two children with different levels of involvement needs to settle who controls the board, how dividends will be paid, and what happens if one wants to exit later. Our article on when a partner wants out covers the valuation side of that last question.
The pre-sale checklist
Work through these before you meet a buyer or announce a handover:
Clean the last four years of tax returns. Reconcile income tax, VAT and TDS filings with the books. Open assessments reduce price or stall the deal.
Normalise the profit. List every family salary, personal expense and related-party rent, and restate them at market terms.
Separate personal and business assets. Land used by the business but owned by the family, vehicles in personal names, and guarantees given by the founder all need a clear decision.
Get an independent valuation range. Use more than one method and document the assumptions so the figure can be defended to a buyer and to the IRD.
Map the shareholding history. Work out how much ownership has already changed in the last three years so you know where the Section 57 line sits.
Decide the structure early. Personal holding or company holding, share sale or asset sale, one step or staged.
Confirm the withholding mechanics. Agree in writing who calculates the gain, who deposits the withholding and when, and keep the challan with the company records.
Update the share register and OCR filings. The transfer is not complete until the Office of the Company Registrar records it.
Plan the people. Key staff, bank relationship managers and major customers should hear about the change in a controlled way.
How long does preparation take?
There is no fixed timeline, but a business that has clean books, a documented valuation and settled family agreements can move through a sale in a few months once a buyer is found. A business that starts from informal records usually needs a full financial year of clean-up before a serious buyer will commit. The cost of that year is almost always lower than the discount a buyer applies to messy books.
Frequently asked questions
Is the gain on selling shares in a family private company taxed in Nepal?
Yes. The gain on disposal of shares in a resident company is subject to withholding under Section 95A, at 10% for a resident individual and 15% for a resident entity on unlisted shares.
Who deducts the tax when shares in a private company are sold?
For an unlisted company, the company whose shares are transferred collects the withholding before recording the transfer. The seller should still keep the deposit receipt.
Does selling 60% of my company affect the company's own tax?
It can. A change of 50% or more in ownership within three years can trigger Section 57, under which the company is treated as having disposed of its assets and liabilities at market value.
What is the tax cost of shares I inherit?
Under Section 44, inherited property is treated as acquired at its market value at the time of transfer on death, and that becomes your cost for a later sale.
Can I just transfer shares at paid-up value to my buyer?
The document may say so, but the IRD can assess the transaction at market value. Recording an artificial price creates tax, interest and penalty exposure for both parties.
For the tax on gains from selling shares or property, see our capital gains questions and answers.
Planning a sale or handover?
Veritas helps Nepali owners prepare a defensible valuation, clean the tax position and plan the structure before a sale or succession. See our business valuation service or read what a buyer will check in due diligence.
General information only, not advice. Rules and rates should be confirmed against the current Income Tax Act, Finance Act and IRD directives before any transaction.


